Your retirement, all in one plan.
Fee-only planning for people approaching retirement and already in it.
Who I work best with
My work is built around the years just before and after retirement. Here’s how to tell if a call makes sense.
Schedule a call if you
- Plan to retire in the next 10 years, or already have
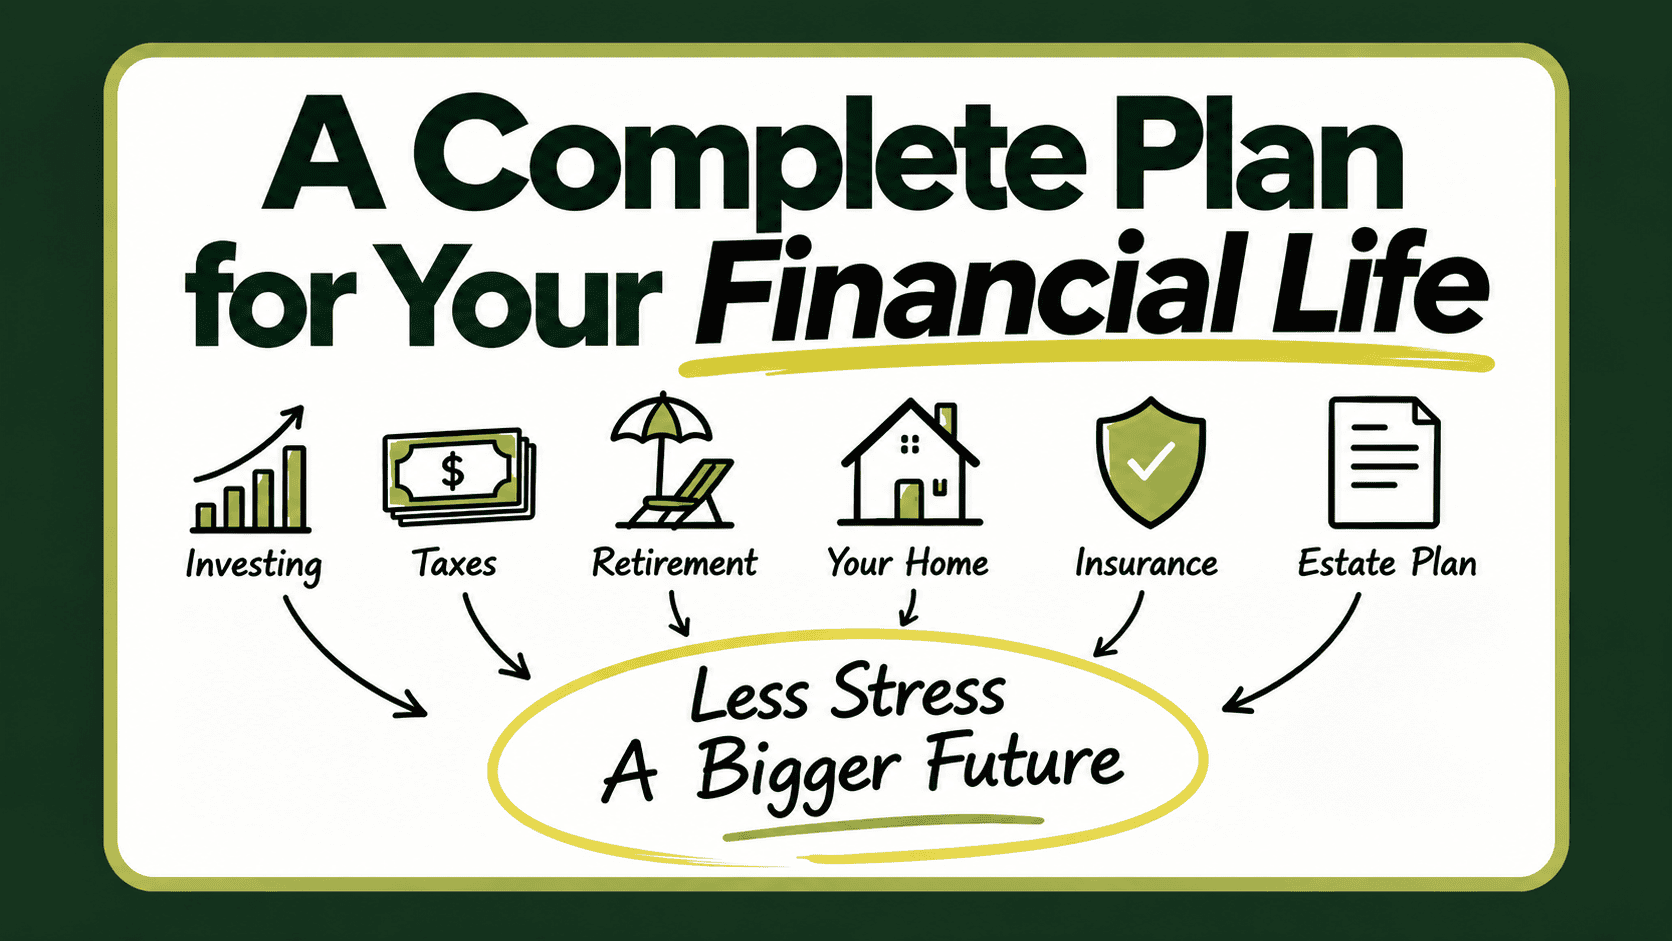
- Want income, taxes, Social Security, Medicare and your estate in one plan
- Want one advisor you work with directly, for the long run
Probably not a fit if you
- Want stock tips or someone to try to beat the market
- Are shopping for an insurance or annuity product
- Prefer to handle everything yourself, without ongoing advice
 Book a call
20 minutes by phone with Scott Brooks, CFP®
Industry-leading tools, chosen for you.
As an independent firm, I don’t have to use any particular software. I get to choose, so I use the tools I think give the clearest answers for your retirement.
Screenshots show sample data. Brooks Wealth Management is not affiliated with these companies and receives no compensation from them.
More than investment management.
Investments matter. But in retirement, the bigger value often comes from coordinating the decisions around the portfolio.
| What the relationship includes | Brooks Wealth Management | Investment-only |
|---|---|---|
| Investment Plan | ✓ | ✓ |
| Cash Flow & Income Plan | ✓ | — |
| Tax Plan | ✓ | — |
| Healthcare Plan | ✓ | — |
| Lifestyle Plan | ✓ | — |
| Risk Management Plan | ✓ | — |
| Estate Plan | ✓ | — |
This comparison illustrates the difference between a planning-first relationship and one focused only on investment management. Other advisors may offer different services.